
Separate Venue Receipt from Putting Gifts on Event Tables
Define where gift delivery ends, which venue tasks need separate approval, and the evidence needed to fund receipt, internal transfer and table placement.
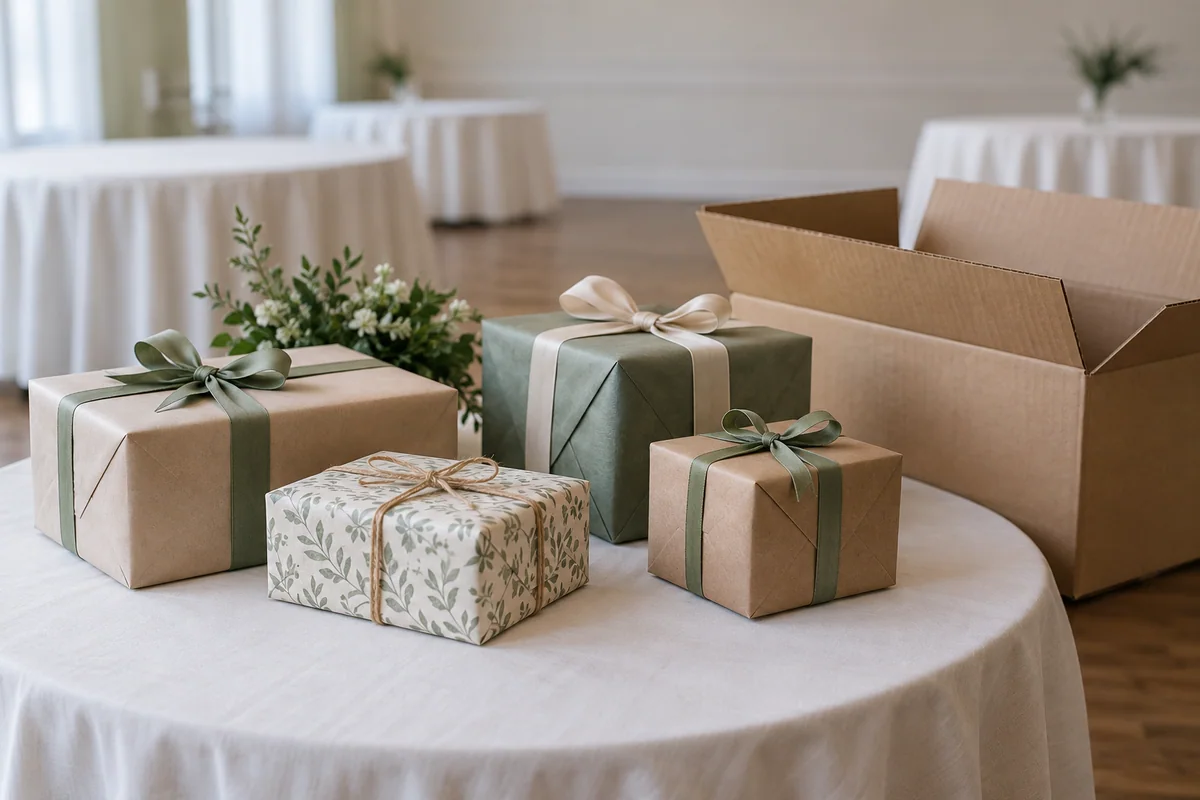
A delivery addressed to an event venue is not yet a plan for putting the right gifts in front of attendees. Before approving transport, name the point where the delivery task finishes and the person responsible for each remaining movement. Price the missing tasks while the event team can still make a choice.
This decision starts with finished gifts and an approved recipient allocation. It does not redesign the gift sets or decide which variant belongs at each table. Its purpose is to connect carriage, venue receipt and attendee presentation through explicit task agreements, so a low transport figure is not mistaken for a complete event handover budget.
Name the endpoint precisely
Replace “deliver to the venue” with the receiving point the provider has actually agreed to serve. Then ask the venue contact to confirm that it can accept the proposed delivery there. A named reception point, a storage area and an event room describe different endpoints, even inside the same building.
Keep the appointment question separate. Record whether a receiving slot is required, who requests it, who confirms it and which evidence establishes that confirmation. A requested slot remains a request. Do not build the gift-placement plan around a date or access arrangement that the responsible venue contact has not accepted.
The International Trade Administration’s Incoterms overview explains that these rules allocate certain buyer and seller responsibilities, costs and risks, but do not cover all sale conditions. For this worksheet, treat table placement and any receiving appointment as tasks requiring explicit scope confirmation; an Incoterms label alone is not their booking evidence.
Start with an event-ready gift definition
Record the approved finished-set reference, the current recipient-group demand and the event owner’s required usable-at-event state. That state might be closed gifts presented at designated tables, or complete groups handed to named event staff. Choose one; the two outcomes require different tasks.
Use the existing group allocation as an input. Do not ask the venue handler to decide which recipient should receive a different variant, or to open individual packs to infer the allocation. If a group is unresolved, identify it as an exception for the organiser before pricing its final placement.
Separate placement from assembly. If the proposed gifts still need ribbon tying, insert placement or other finishing, those activities require their own defined scope. Calling the work “table placement” must not quietly add gift assembly or a product check to somebody’s job.
Build the venue-task responsibility sheet
Use the following columns for each proposed service combination. The rows are fictional planning states, not confirmed venue services. Attach the named owner, evidence reference and charge status to each task entry.
| Named delivery point | Receiving appointment | Internal movement | Table placement | Empty-carton removal | Fee owner |
|---|---|---|---|---|---|
| Agreed reception point only | Requirement and booking unconfirmed | Excluded | Excluded | Unresolved | Campaign buyer for quoted carriage; other tasks unassigned |
| Same reception point plus transfer | Separate confirmation required | Proposed transfer to named room | Excluded | Unresolved | Buyer to approve transfer payer |
| Same point through presentation | Separate confirmation required | Proposed transfer to named room | Proposed placement against approved allocation | Still unresolved unless expressly included | Buyer to approve each task and payer |
“Unresolved” is different from “included at no extra charge.” Ask for the exact task description, provider and commercial treatment before changing that status. If an existing venue agreement covers a task, cite that agreement and confirm the relevant event scope rather than assuming an earlier booking applies.
Identify the handover between providers. Who tells the internal handler the gifts have been received? Who confirms that the room is ready? Who can authorise a change if the agreed room cannot be used? These questions expose responsibility gaps without prescribing handling equipment or an unloading method.
Work the budget only to the stated endpoint
Consider a wholly fictional offer covering carriage to an agreed reception point at 210 CU. Separately proposed internal transfer is 70 CU and table placement is 50 CU. CU means fictional currency units. None of these amounts is a carrier, supplier or venue rate, and no service or appointment is assumed available.
If the buyer approves both additional tasks, the covered-scope subtotal is:
210 CU carriage + 70 CU internal transfer + 50 CU table placement = 330 CU.
The addition beyond carriage is 120 CU. If only transfer is approved, the covered subtotal would be 280 CU, but gifts placed on tables would remain outside that decision. Writing 210 CU in a budget labelled “gifts on event tables” would leave the last two tasks unfunded in this example.
The 330 CU is not complete landed cost. It excludes the gifts, decoration, any other origin or transport charges, duties and taxes, storage, waiting, repeat attempts, empty-carton removal and other unlisted work. Whether any of these actually applies must be established for the real order. Do not turn an unknown into a zero merely to finish the arithmetic.
Compare another proposal only after checking the same receiving point, gift allocation, internal destination, placement outcome and task exclusions. A higher figure covering placement cannot be called a higher carriage price simply because it appears next to the reception-only figure.
Decide what to release and what to hold
Approve the narrowest complete scope that meets the event plan. If organised event staff will perform placement, obtain the responsible person’s agreement and record any associated budget separately. Staff being present at the event is not evidence that they have accepted this task.
If the venue has not confirmed receipt or room access, keep the affected task approval conditional. Ask the event owner to choose between securing the missing arrangement and changing the handover plan. Do not instruct a driver or handler to improvise access, storage or placement.
A changed recipient allocation can also change the venue work without changing the number of transported cartons. More placement points, a different room or a revised presentation state should return the relevant rows for confirmation. Preserve the approved carriage scope while identifying exactly what requires a new answer.
Close with evidence of the right milestone
Agree how the people involved will report progress and how often. Keep the written task scope, receipt evidence, internal handover confirmation, placement confirmation, exception owner and next decision together. A carrier delivery update establishes neither correct table allocation nor usable gifts at the event. Ask the event owner for the evidence appropriate to the outcome it requested.
Use the party-supplies guide for broader event buying and the gift shipping-cost guide for the wider cost foundation. For a quote enquiry, describe the finished gifts, approved group demand, named receiving point and requested final presentation. Ask which tasks can actually be offered and which need a separate agreement.
Frequently asked questions
Does venue delivery include putting gifts on tables?
Only when the actual written scope includes that task. Name the receiving point, internal movement and final presentation separately, then identify the provider and payer for each. A delivery address, shipping term or requested appointment is not evidence that table placement has been agreed.
Which missing fee would make the fictional 330 CU comparison incomplete?
Empty-carton removal is still unresolved, as are any applicable waiting, storage or repeat-attempt charges. The 330 CU covers only the invented carriage, transfer and placement amounts. Goods, other transport lines and tax treatment remain outside it, so it is not a complete landed-cost figure.
What should change when the table allocation changes?
Send the revised allocation to the event decision owner and the proposed placement provider. Ask whether the number of placement points, destination room, task scope or charge changes. Do not assume unchanged carton quantity means unchanged event work; keep unaffected carriage decisions distinct.
What evidence is needed before approving venue handling?
Obtain the venue receiving arrangement, exact task agreement, gift-group allocation, price or labelled allowance, named payer and exception owner. Agree the evidence for receipt, transfer and placement separately, plus reporting frequency. Any appointment or available service still lacking confirmation must remain an open condition.
Sources
Discuss a sourcing request related to this article.Separate Venue Receipt from Putting Gifts on Event Tables